Loading blog posts...
April 24, 2026 • 3 min read
Our goal today is to dig into the income statement from one of the semiconductor industry's most critical behind-the-scenes players and see what we can learn from its latest financial results. Lam Research Corporation (LRCX) is a heavyweight in the semiconductor capital equipment market. Specifically, they design and build the wafer fabrication equipment (WFE)—like advanced deposition and etch tools—that chipmakers desperately need to manufacture modern semiconductors.
Let's unpack the numbers from their latest 10-Q filing to see how the surging demand for artificial intelligence infrastructure is rippling through the semiconductor supply chain.
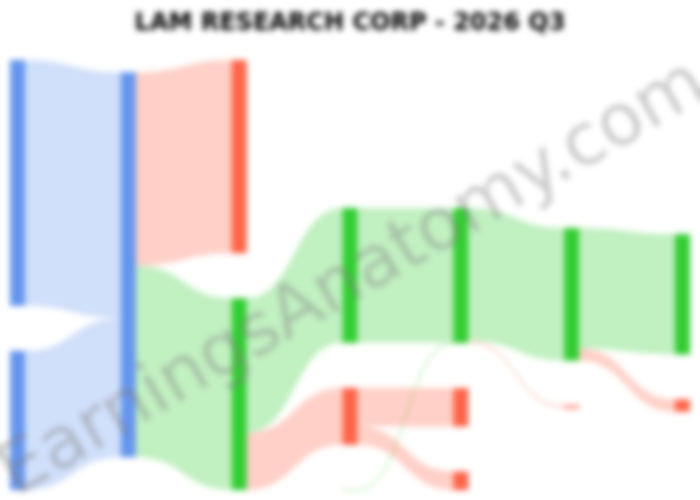
The quarter ending March 29, 2026, was a record-setting period for Lam Research. The company generated $5.84 billion in total revenue, a significant 24% year-over-year jump from the $4.72 billion reported in the same quarter last year. This growth highlights a robust demand environment, which the company's management attributes to the semiconductor industry's expansion to meet the needs of AI.
This growth came from both of its primary revenue streams. "Systems revenue," which includes new fabrication tools, grew to $3.73 billion. Meanwhile, "Customer support-related revenue," which covers services, spares, and upgrades, also hit a record $2.11 billion, indicating that existing fabrication plants are running at high utilization.
The following flow diagram provides a visual breakdown of Lam Research's quarterly income statement, from its revenue sources to its final net income.
Higher sales volumes and improved factory efficiencies also translated into strong profitability. Gross margin for the quarter was $2.91 billion, or 49.8% of revenue, a solid improvement from 49.0% in the prior year. This margin expansion is a positive sign of the company's operational leverage and pricing power.
After accounting for R&D and administrative expenses, Lam posted an operating income of $2.05 billion. The bottom line was a net income of $1.83 billion, translating to a diluted earnings per share (EPS) of $1.45. This represents a substantial increase from the $1.33 billion in net income from the same quarter in 2025.
Looking at the geographic breakdown, the company's sales remain heavily concentrated in Asia, with China (34%), Korea (23%), and Taiwan (23%) representing the top three markets. This underscores the region's central role in global semiconductor manufacturing.
In conclusion, Lam Research's latest earnings report paints a clear picture of a company firing on all cylinders. The powerful tailwind from AI is driving record demand for the sophisticated equipment needed to produce next-generation chips. While the company operates in a famously cyclical industry and faces risks from geopolitical tensions and a concentrated customer base, its current performance suggests a period of sustained growth ahead for this critical "pick-and-shovel" player in the tech ecosystem.
Last updated: April 24, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
Lam Research (LRCX) Q1 FY2027: Revenue Surges 54% as Memory Rebounds
Oct 22, 2026
Read
Lam Research (LRCX) FY26 10-K Analysis: Riding the AI CapEx Wave
Aug 9, 2026
Read
Lam Research (LRCX) 10-Q Analysis: China Demand & Foundry Strength
Jan 30, 2026
Read
Lam Research (LRCX) Q3 2025: Foundry and China Fuel Strong Growth
Oct 25, 2025
Read