Loading blog posts...
August 9, 2026 • 4 min read
When you think of the ongoing artificial intelligence revolution, the first names that come to mind are likely the chip designers producing the high-powered processors powering these massive models. But behind those household names is an entire ecosystem of unsung heroes—companies like Lam Research Corp (LRCX). Lam is a dominant force in semiconductor capital equipment, manufacturing the highly complex wafer fabrication tools (specifically plasma etch and deposition systems) that physical chipmakers like TSMC and Samsung need to print microscopic circuits onto silicon.
If you want to know how the AI "pick and shovel" business is doing, look no further than Lam Research’s latest 10-K filing for the fiscal year ended June 28, 2026. Let's unpack their income statement to see how the industry's massive capital expenditure cycle is flowing straight to their bottom line.
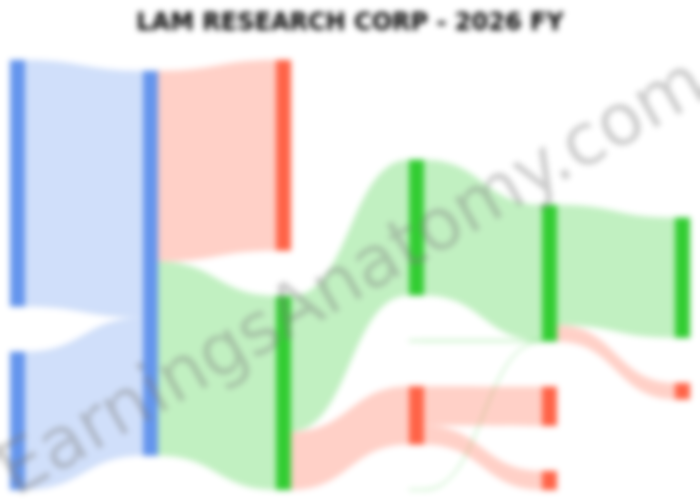
Lam Research recorded a staggering $23.2 billion in total revenue for FY 2026, representing a massive 26% year-over-year growth from $18.4 billion in FY 2025.
This revenue essentially comes from two main buckets. The first is Systems Revenue, which hit $14.9 billion (64% of total sales). This segment represents the sale of brand new, leading-edge equipment used in advanced chipmaking. Foundries (companies that manufacture chips for fabless designers) drove the lion's share of this demand, jumping from 45% of sales last year to 54% this year. The second bucket is Customer Support-Related Revenue, which brought in $8.3 billion (36% of sales). This is a highly lucrative, recurring revenue stream composed of spare parts, equipment upgrades, and services for their existing installed base of machines.
The surge in Systems Revenue is a direct reflection of the global race to build 2-nanometer and 3-nanometer logic chips, as well as the high-bandwidth memory (HBM) required to feed data-hungry AI accelerators.
It’s one thing to sell more equipment, but it’s another to do it increasingly efficiently. Lam Research flexed its pricing power and operational efficiency this year. Gross profit soared to $11.7 billion, bumping gross margin up 180 basis points to an exceptional 50.5%.
Even while heavily investing in future innovations—Research and Development (R&D) expenses grew to nearly $2.4 billion—Lam's operating income jumped to $8.2 billion, yielding a highly profitable 35.3% operating margin.
After accounting for taxes and other minor expenses, Lam Research delivered an impressive $7.3 billion in net income, representing a 31% net margin. This is a 35.6% explosion in pure profit compared to the $5.4 billion generated in FY 2025. Diluted earnings per share (EPS) clocked in at a robust $5.76.
A look at Lam's geographic revenue breakdown reveals the center of gravity in the semiconductor manufacturing world. China remained Lam's largest single market, accounting for a massive 34% of total revenue ($7.9 billion). Taiwan and Korea followed with 22% and 19%, respectively, reflecting the heavy presence of foundry and memory giants in those regions.
However, this geographic concentration doesn't come without risks. As highlighted in the filing's risk factors, the company remains highly exposed to changing domestic and international trade regulations. Any tightening of export controls or trade disputes—particularly between the U.S. and China—could materially inhibit their ability to sell certain leading-edge products into their largest market.
Lam Research's FY 2026 results confirm that the AI supercycle is far from a software-only phenomenon. The physical infrastructure required to manufacture next-generation semiconductors is driving record-breaking cash flows for the equipment providers. As major chipmakers continue to expand fabrication capacity and transition to increasingly complex chip architectures, Lam Research appears firmly entrenched as a foundational pillar of the global tech economy.
Last updated: August 9, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
Lam Research (LRCX) Q1 FY2027: Revenue Surges 54% as Memory Rebounds
Oct 22, 2026
Read
Lam Research Q3 2026 Financial Analysis: Record Revenue Driven by AI Demand
Apr 24, 2026
Read
Lam Research (LRCX) 10-Q Analysis: China Demand & Foundry Strength
Jan 30, 2026
Read
Lam Research (LRCX) Q3 2025: Foundry and China Fuel Strong Growth
Oct 25, 2025
Read