Loading blog posts...
October 23, 2026 • 4 min read
American Express delivered another strong quarter of growth in the third quarter of 2026, driven by resilient premium consumer spending and solid credit performance. By examining the income statement details in the company's latest 10-Q filing, we can assess how revenue momentum, credit quality, and expense management are driving bottom-line profitability.
During the third quarter of 2026, American Express generated $20.1 billion in total revenues net of interest expense—an increase of 9% compared to the prior-year period. Net income climbed 28% year-over-year to $3.71 billion, pushing diluted earnings per share (EPS) up 31% to $5.42.
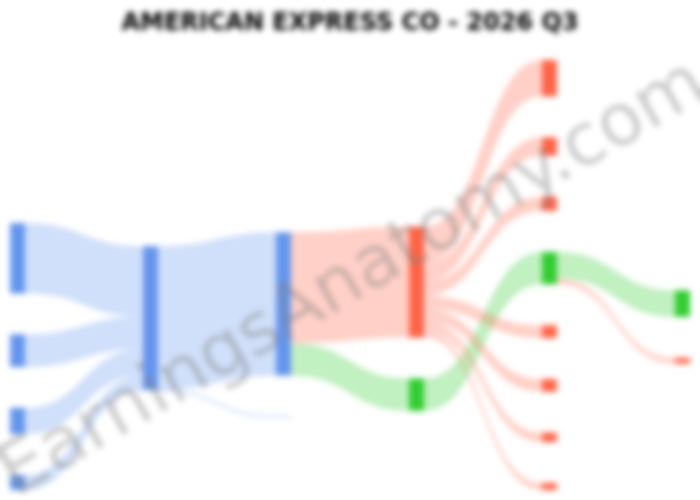
The chart below maps how top-line revenues from card fees, merchant discount fees, and net lending interest flowed through expenses and credit loss provisions to produce the quarter's net profit.
In the visual breakdown above, segment revenues total $20.16 billion across the four primary divisions, offset by $96 million in Corporate & Other adjustments and intersegment eliminations, arriving at the reported net consolidated revenue of $20.06 billion.
A key contributor to the bottom line this quarter was a one-time gain of $982 million included within operating expenses (under Other, net). This gain stemmed from the sale of American Express's equity method investment in Global Business Travel Group (Amex GBT), the publicly traded B2B travel management platform that was spun off as a joint venture in 2014.
Revenue momentum reflected both transaction volume and subscription-like card fee gains:
Performance across Amex's reporting segments highlighted both consumer resilience and disciplined risk underwriting:
Credit quality remained a notable strength. Consolidated provisions for credit losses fell 23% to $985 million, aided by a $235 million reserve release on card balances. The total card balance net write-off rate ticked down to 2.1% (compared to 2.2% in Q3 2025), and 30+ day past-due loans held steady at a low 1.2%.
American Express continues to differentiate itself from traditional bank issuers like JPMorgan Chase and open network operators like Visa and Mastercard through its closed-loop network and affluent cardholder demographic. While sustaining card fee expansion and travel spend will test consumer price sensitivity in an evolving macroeconomic backdrop, Amex enters the final stretch of 2026 with an enviable 10.9% Common Equity Tier 1 capital ratio and industry-leading customer retention.
Last updated: October 23, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
American Express Q2 2026: Premium Strategy Drives Record Revenue and Fee Growth
Jul 27, 2026
Read
American Express Q1 2026: Premium Strategy Drives 11% Revenue Growth
Apr 24, 2026
Read
American Express 2025: Analyzing the Premium Membership Engine
Feb 6, 2026
Read
American Express Q3 2025 Analysis: Revenue Growth, Rising Costs, and Rock-Solid Credit
Oct 17, 2025
Read