Loading blog posts...
July 27, 2026 • 3 min read
American Express closed the second quarter of 2026 with a record performance, offering a clear look into how its premium-focused strategy is performing. Digging into the income statement from their latest 10-Q filing reveals how the world's largest travel-and-lifestyle-focused card issuer is converting affluent cardholders into sustained top-line growth—and where the operational costs of that strategy are showing up.
American Express occupies a unique position in the financial ecosystem: it functions as both a payment network (competing with Visa and Mastercard) and a card issuer and bank (competing with JPMorgan Chase and Citi). This dual role allows Amex to generate revenue from merchant discount fees, cardholder annual fees, and net interest income on revolving balances.
Total revenue net of interest expense reached $19.6 billion, an increase of 10% year over year. Net income rose 8% to $3.1 billion, yielding $4.53 per diluted share (an 11% increase in EPS, bolstered by common share repurchases that reduced diluted share count by 3%).
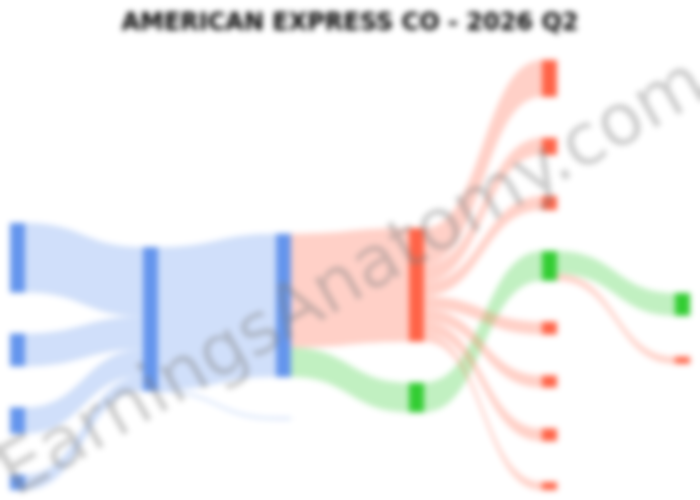
Here is how the quarter's revenues and expenses flowed through to net income:
The flow chart reflects a small -$104 million "Corporate & Other" revenue adjustment. This represents intersegment eliminations and unallocated corporate-level items that net out when reconciling Amex's four main operating segments—U.S. Consumer Services, Commercial Services, International Card Services, and Global Merchant and Network Services—to consolidated total revenues.
A key engine behind this performance was net card fees, which grew 15% to $2.9 billion, alongside discount revenue (merchant transaction fees), which rose 9% to $10.2 billion. Card fee growth outpacing transaction volume growth highlights Amex's ability to drive higher price points for its premium cards. The average annual fee per proprietary card rose to $131 from $117 in the prior-year period.
Delivering premium card value comes at a significant cost. Card Member services expense surged 50% year over year to $1.9 billion, driven by enhanced Card Member benefits, higher benefit utilization, and updates to flagship offerings such as the U.S. Platinum Card.
Simultaneously, Card Member rewards—the company's largest single expense line—increased 9% to $5.1 billion, while marketing expenses rose 6% to $1.65 billion as Amex invested in customer acquisition. The company acquired 3.0 million new proprietary cards during the quarter, bringing total cards-in-force to 155.1 million. Total billed business (card spending) increased 9% to $455.8 billion, demonstrating strong engagement among cardholders despite higher fee structures.
Credit performance remained strong throughout the quarter. Total provisions for credit losses declined 23% to $1.1 billion, aided by a $190 million net credit reserve release on card balances. The net write-off rate on card balances held steady at 2.2%, while 30+ day delinquencies for consumer and small business accounts remained low at 1.2%.
Amex generated a return on average equity (ROE) of 36.4% and maintained a Common Equity Tier 1 (CET1) capital ratio of 10.4%. Capital returned to shareholders included $2.2 billion in share repurchases and $645 million in common stock dividends ($0.95 per share, a 16% increase over Q2 2025).
American Express's second-quarter results show that its affluent target demographic continues to support both fee growth and spending volume. While escalating benefit costs represent an ongoing operational commitment, strong credit quality and rising fee income provide a solid foundation as Amex navigates a competitive premium card market.
Last updated: July 27, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
American Express Q3 2026 Earnings: Premium Spend Drives 28% Profit Surge
Oct 23, 2026
Read
American Express Q1 2026: Premium Strategy Drives 11% Revenue Growth
Apr 24, 2026
Read
American Express 2025: Analyzing the Premium Membership Engine
Feb 6, 2026
Read
American Express Q3 2025 Analysis: Revenue Growth, Rising Costs, and Rock-Solid Credit
Oct 17, 2025
Read