Loading blog posts...
February 6, 2026 • 4 min read
The iconic "Centurion" logo of American Express is synonymous with premium travel and high-end spending. But beneath the glossy card designs lies a complex financial engine that balances merchant fees, cardholder subscriptions, and lending risk. We are going to dig into the income statement from their latest 10-K filing to see how the company performed in 2025 and what the numbers tell us about the health of the high-end consumer.
American Express operates a "closed-loop" network, meaning they act as both the issuer (giving you the card) and the acquirer (processing the payment for the merchant). This allows them to capture economics from both sides of a transaction.
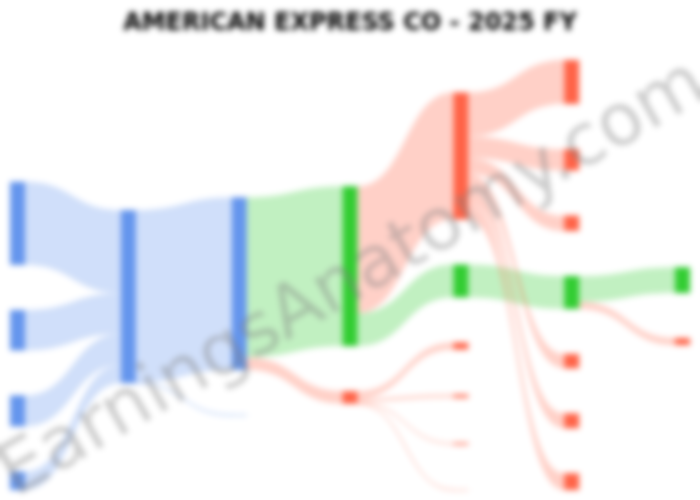
To visualize how these revenue streams cascade down into net income, take a look at the flow diagram below:
Note: In the diagram above, "Corporate & Other" represents corporate functions and intersegment eliminations, which resulted in a slight negative revenue adjustment.
For the full year of 2025, American Express reported $72.2 billion in total revenues net of interest expense, a robust 10% increase year-over-year. Net income followed suit, rising 7% to $10.8 billion.
What stands out immediately is the composition of that revenue. While many banks rely heavily on interest income (lending money), Amex’s bread and butter remains Discount Revenue—the fees merchants pay when a cardmember swipes their card. This line item grew 6% to $37.4 billion, driven by an 8% increase in billed business.
However, the real star of the show is Net Card Fees. This revenue stream surged 18% to nearly $10 billion. This suggests that despite inflation and economic uncertainty, customers are increasingly willing to pay hefty annual fees for premium cards (like the Platinum and Gold cards) to access perks and status.
The defining feature of the American Express business model is its high expense base related to keeping customers happy. You can't charge premium fees without offering premium value.
Essentially, Amex is running a high-stakes arbitrage: they collect massive fees from merchants and cardholders, then reinvest a significant portion of that into rewards and services to ensure those cardholders keep spending.
In the current economic environment, all eyes are on credit quality. Are consumers starting to crack?
Amex reported Provisions for Credit Losses of $5.3 billion, a modest 1% increase from the prior year. More importantly, the Net Write-off Rate (principal, interest, and fees) remained stable at 2.3%. This stability highlights the resilience of Amex’s prime and super-prime customer base compared to broader consumer lenders who often see higher volatility during economic shifts.
The company reports across four main segments, but the U.S. Consumer Services (USCS) division remains the powerhouse. USCS revenue grew 11% to $34.8 billion, driven by loan growth and fee increases.
Interestingly, International Card Services (ICS) was the fastest-growing segment, with revenue up 13%, outpacing the domestic business. This indicates that Amex's strategy to expand its premium model globally is gaining traction, despite currency headwinds.
American Express closed 2025 with strong momentum, leveraging its distinct "spend-centric" model. While the costs to maintain its premium ecosystem are rising—specifically in rewards and services—the company's ability to raise card fees by double digits proves the strength of its brand moat. For investors and observers, the key takeaway is that the affluent consumer remains resilient, continuing to spend and travel even as the cost of membership rises.
Last updated: February 6, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
American Express Q3 2026 Earnings: Premium Spend Drives 28% Profit Surge
Oct 23, 2026
Read
American Express Q2 2026: Premium Strategy Drives Record Revenue and Fee Growth
Jul 27, 2026
Read
American Express Q1 2026: Premium Strategy Drives 11% Revenue Growth
Apr 24, 2026
Read
American Express Q3 2025 Analysis: Revenue Growth, Rising Costs, and Rock-Solid Credit
Oct 17, 2025
Read