Loading blog posts...
August 2, 2026 • 3 min read
Understanding how major financial services firms generate profit through periods of aggressive expansion requires a close look at their core financials. Headquartered in Daytona Beach, Florida, Brown & Brown, Inc. (BRO) is one of the largest insurance brokerages in the world, connecting commercial, public, and individual clients with customized risk-mitigation solutions. Let's unpack the numbers from their latest 10-Q filing to see how the business is performing, how recent strategic moves are paying off, and what we can learn from their second-quarter 2026 results.
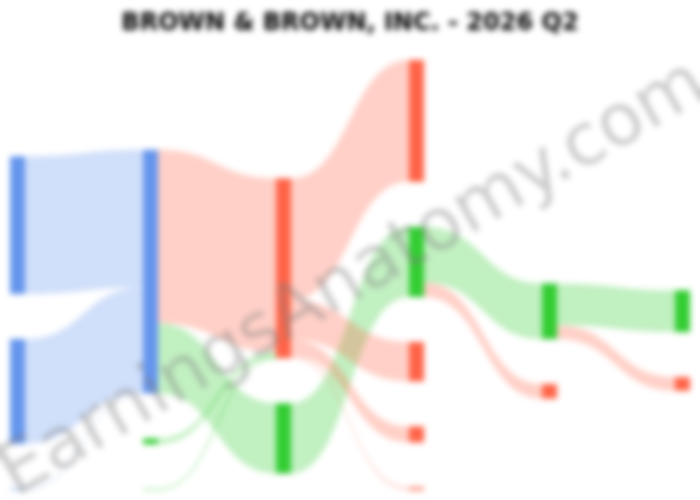
The unallocated revenue item of $8 million shown above represents corporate-related items and intercompany revenue eliminations that are not assigned to either primary reportable operating segment.
Brown & Brown delivered total revenues of $1.68 billion for the quarter ended June 30, 2026, marking a robust 30.4% increase compared to $1.29 billion in Q2 2025. This strong top-line momentum was primarily powered by the company's acquisition of Accession Risk Management Group in mid-2025, which added significant market reach and scale to both operating divisions.
However, underlying core performance presented a more complex picture. Organic revenue—which isolates core growth by excluding the impact of mergers, acquisitions, divestitures, and foreign currency movements—declined slightly by 0.7%. This dip was driven by moderating property insurance rates and structural changes in specialized consulting lines.
Offsetting this drag was a sharp 88.9% surge in profit-sharing contingent commissions (reaching $85 million), which are performance-based payments received from insurance underwriters for delivering favorable loss ratios. Factoring in contingents, organic revenue grew by 0.7%.
Operating expenses for the quarter stood at $1.19 billion, with employee compensation and benefits serving as the largest cost driver at $838 million (50.0% of total revenue). Total expenses reached $1.29 billion, including $100 million in interest expense—nearly double the $51 million recorded in Q2 2025—reflecting the debt incurred to finance major acquisitions.
Two notable non-cash credits helped temper expense growth:
Looking at the business divisions:
Bottom-line net income attributable to the company rose 24.7% to $288 million, delivering diluted earnings per share (EPS) of $0.84, up from $0.78 in the prior-year period.
Brown & Brown's quarterly results reflect the classic dynamics of an acquisition-led growth strategy: substantial top-line scale and steady profit margins (net margin at 17.2%), balanced against higher debt servicing costs. While slowing commercial property rate increases present ongoing market headwinds in competing against global peers like Marsh McLennan and Aon, Brown & Brown's expanded distribution footprint and tight expense execution keep its market standing firm.
Last updated: August 2, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.