Loading blog posts...
February 21, 2026 • 3 min read
Let's dig into the income statement from one of the largest personal lines insurers in the United States to see how things are going and what we can learn from it. Allstate Corp, famous for its "You're In Good Hands" slogan, recently published its annual 10-K filing, and the financial results reveal a massive surge in bottom-line profitability driven by strategic asset sales and vastly improved underwriting margins.
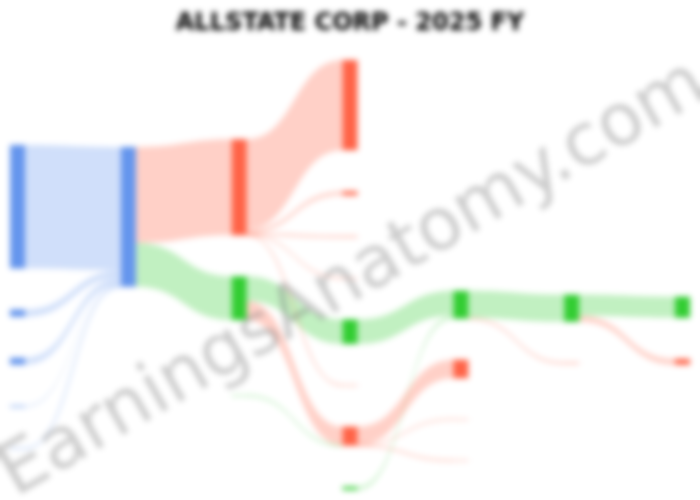
Here is a visual breakdown of how Allstate's revenue flows through various costs and claims to generate the final net income:
Allstate's total revenues climbed to $67.7 billion in 2025, up from $64.1 billion in 2024. The primary engine of this growth was Property and Casualty (P&C) insurance premiums, which hit $60.5 billion. However, the most compelling insight from the filing isn't just the top-line growth; it's the operational efficiency of the underlying insurance business.
In the insurance industry, the combined ratio is the ultimate scorecard. It measures incurred losses and operational expenses as a percentage of earned premiums. A ratio under 100% indicates an underwriting profit, while anything over 100% means the company is paying out more than it's taking in.
In 2025, Allstate's Property-Liability combined ratio improved drastically to 85.2%, down from a much tighter 94.3% the prior year. This implies that for every dollar of premium earned, Allstate kept nearly 15 cents in underwriting profit—a highly lucrative margin for a massive legacy insurer.
A closer look at the claims data shows how Allstate achieved this margin. Interestingly, catastrophe losses—claims resulting from severe weather events like wind, hail, and wildfires—remained relatively flat year-over-year at roughly $4.96 billion.
The real boost to the bottom line came from a massive $1.81 billion favorable prior-year reserve reestimate. Insurance companies must estimate and set aside reserves for claims that have occurred but haven't been fully settled. As time passes and claims are resolved, a company might find that it overestimated the required payouts. In 2025, Allstate realized it had set aside more money than necessary in previous years, allowing the company to release those reserves back into its earnings, significantly lowering its overall loss ratio.
While core insurance operations fired on all cylinders, another major driver of 2025’s massive profit jump was a deliberate narrowing of the company's focus.
The filing highlights a $1.6 billion gain on the disposition of operations. This windfall came primarily from the sale of Allstate's Employer Voluntary Benefits (EVB) and Group Health businesses, which were offloaded in the second and third quarters of the year. By shedding these segments, Allstate is doubling down on its core competencies: auto and homeowners insurance, alongside its expanding Protection Services division (which includes offerings like identity protection and roadside assistance).
Ultimately, Allstate's net income applicable to common shareholders soared to $10.16 billion (or $38.56 per basic share) in 2025, more than doubling the $4.55 billion generated in 2024.
The personal insurance market has been notoriously difficult to navigate over the last few years. Competitors across the board, including giants like State Farm and Progressive, have wrestled with inflation driving up vehicle repair costs and increasingly volatile weather events hammering homeowners. Yet, by aggressively managing pricing, optimizing their reserve buffers, and strategically exiting non-core health segments, Allstate effectively shielded its margins and delivered an exceptionally strong year.
Last updated: February 21, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.