Loading blog posts...
April 22, 2026 • 3 min read
3M, the global materials science and manufacturing giant, recently underwent a major transformation by spinning off its healthcare division into a new company, Solventum. This move refocused 3M on its core industrial and consumer markets. A look at the company's first-quarter 2026 financial report reveals a complex but ultimately positive story about the health of its ongoing operations. While the headline net income number shows a steep decline, a deeper dive shows a more profitable core business emerging.
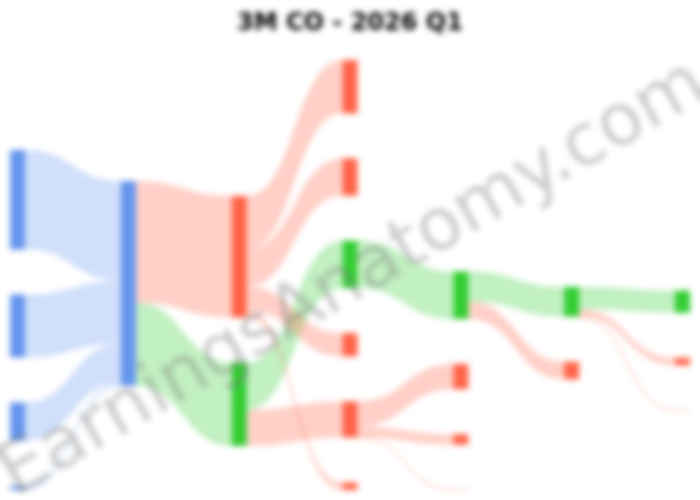
For the first quarter of 2026, 3M reported total sales of $6.0 billion, a modest 1.3% increase from the same period last year. To understand how this revenue was converted into profit, the following flow diagram breaks down the major costs and expenses.
The diagram and financial tables include a "Corporate" revenue line item of $121 million. According to the filing, this primarily includes fees from transition arrangement agreements with divested businesses, including the newly independent Solventum.
At first glance, the numbers look concerning. GAAP Net Income attributable to 3M fell sharply to $653 million, or $1.23 per share, compared to $1.1 billion, or $2.04 per share, in the first quarter of 2025. However, this drop is almost entirely due to non-operational, post-spin-off accounting adjustments.
The key item was a $356 million pre-tax charge related to the "change in value" of 3M's retained ownership stake in Solventum. This is a non-cash accounting charge and doesn't reflect the performance of 3M's actual business operations.
When we strip out this noise and look at operating income, a much healthier picture emerges.
This improvement was largely driven by a significant reduction in Selling, General, and Administrative (SG&A) expenses, which fell by over $200 million compared to the prior year, signaling successful cost management and a more efficient operational structure.
3M's performance was led by its largest division, Safety and Industrial, which provides products ranging from industrial adhesives and abrasives to personal safety equipment.
This breakdown shows the current strength of 3M's industrial-facing businesses, which are more than offsetting the sluggishness in its consumer segment.
The first quarter of 2026 demonstrates that the newly focused 3M is on stronger footing. The company's improved operating margin and disciplined cost control are positive indicators of its underlying health. While the Solventum spin-off created some accounting complexities that dragged down GAAP earnings, the core business is performing well. The primary challenge for 3M remains navigating its significant legal liabilities related to PFAS and Combat Arms earplugs, which continue to represent a major uncertainty for the company's financial future.
Last updated: April 22, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
3M Q3 2026 10-Q Analysis: Margin Expansion, PFAS Exit, and Fire Safety Acquisition
Oct 21, 2026
Read
3M Q2 2026: Why Net Income Jumped 29% While Operating Income Fell
Jul 22, 2026
Read
3M 2025 10-K Analysis: Stability Amidst Transformation
Feb 4, 2026
Read
Inside 3M's Q3 2025 Earnings: Sales Grow, but Profits Fall on Special Charges
Oct 23, 2025
Read