Loading blog posts...
August 11, 2026 • 3 min read
Wells Fargo has spent the better part of the last decade navigating a strict regulatory environment, most notably operating under a punitive $1.95 trillion asset cap imposed by the Federal Reserve in 2018. However, mid-2025 marked a historic turning point when the Fed finally lifted the cap, removing the most significant hurdle to the bank’s expansion.
With the regulatory shackles off, we can look to the bank's latest 10-K filing to see how the numbers are shaping up in this new era of growth.
For the fiscal year ending December 31, 2025, Wells Fargo reported total revenue of $83.7 billion, up from $82.3 billion in 2024. The bank successfully translated this top-line expansion into a robust bottom line, posting a net income of $21.3 billion. This translates to an impressive 25.5% net margin. On a per-share basis, basic earnings per share (EPS) hit $6.34, with diluted EPS at $6.26.
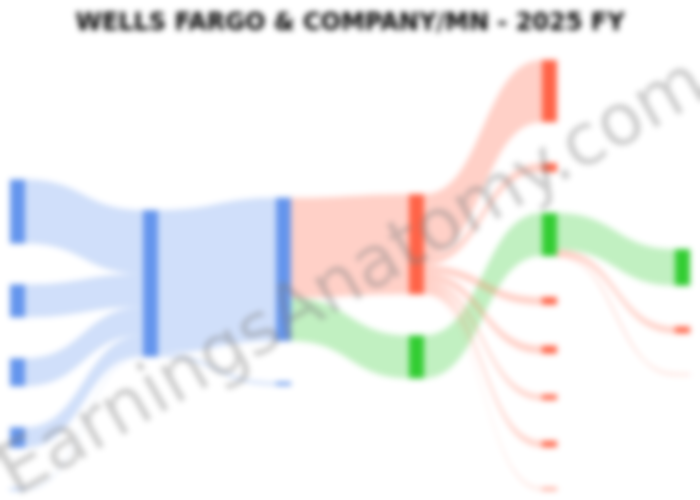
Here is a breakdown of how the bank's revenue flowed through to the bottom line during the year:
You might notice an "Unallocated" or Reconciling Items revenue component of -$1.9 billion in the flow diagram. In banking, reconciling items typically represent corporate treasury functions, accounting eliminations, or timing mismatches that are not tied directly to the core performance of the main customer-facing divisions.
Wells Fargo serves roughly one in three U.S. households, and its Consumer Banking and Lending segment remains the heavy hitter. This division—which handles checking accounts, credit cards, auto loans, and personal lending—generated $37.4 billion in revenue (about 45% of the gross total) and $10.5 billion in operating income.
The bank has also been aggressively building out its Wall Street presence to compete with larger peers. The Corporate and Investment Banking division is seeing the fruits of this labor, bringing in $19.2 billion in revenue and generating a substantial $9.7 billion in operating income—making it the most profitable division by operating margin (50.6%).
Rounding out the business, Wealth and Investment Management generated $16.3 billion, and traditional Commercial Banking added another $12.0 billion to the top line.
A major metric for any bank is its Provision for credit losses—essentially the amount of money set aside to cover loans that borrowers might fail to repay. For 2025, Wells Fargo set aside $3.7 billion, a noticeable drop from the $4.3 billion allocated in 2024. This decrease indicates a relatively healthy loan portfolio and confidence in the credit environment.
On the expense side, total operating expenses came in at $58.5 billion. Despite heavy investments in digital modernization and artificial intelligence, traditional banking remains an intensely human-capital business. Personnel costs accounted for the lion's share of operating expenses at $36.3 billion, followed by technology and equipment at $5.2 billion and occupancy costs at $3.2 billion.
The 2025 results show a bank that is effectively balancing profitability with a massive structural transformation. Now that the Federal Reserve has lifted the asset cap, Wells Fargo is free to expand its balance sheet organically. The bank's renewed push into investment banking and credit card growth is already yielding strong returns. Moving forward, the key challenge will be proving it can aggressively grow its market share while maintaining the stringent risk management controls it spent the last seven years rebuilding.
Last updated: August 11, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
Wells Fargo Q3 2026: Earnings Rise as Margins Narrow and Capital Buffer Shrinks
Oct 29, 2026
Read
Wells Fargo Q2 2026 Earnings: Strong Revenue Growth and VC Gains
Jul 30, 2026
Read
Wells Fargo Q1 2026 Earnings: Growth Amidst Rising Credit Costs
Apr 30, 2026
Read
Wells Fargo Q2 2025: Profit Rises 12% on Lower Credit Provisions
Aug 5, 2025
Read