Loading blog posts...
October 29, 2026 • 3 min read
ServiceNow’s third-quarter results show strong revenue growth translating into less profit. Digging into the enterprise software company’s Q3 2026 10-Q helps explain why: revenue increased 20.5% to $4.11 billion, but higher delivery costs, acquisition-related charges and interest expense pushed net income down 44.8% to $277 million.
ServiceNow provides cloud software that automates work across IT, customer service, human resources and other business functions. Its expanding AI and cybersecurity offerings broaden that platform, while the income statement reveals the financial costs accompanying that expansion.
Subscription revenue rose 20.9% to $3.99 billion, representing approximately 97% of total revenue. Growth extended across regions: North America increased 20.7%, Europe, the Middle East and Africa grew 17.6%, and Asia Pacific and other markets advanced 25.9%.
The bigger issue was delivery economics. Subscription costs increased 58.3% to $1.05 billion, reducing subscription gross margin—the revenue remaining after direct delivery costs—from 79.8% to 73.6%. Professional services and other activities produced a $39 million gross loss, versus breakeven a year earlier.
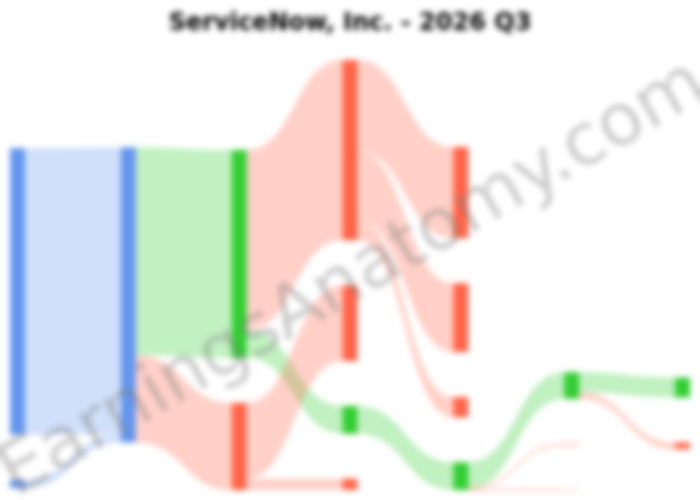
Overall gross margin fell from 77.3% to 70.5%. The diagram below follows the quarter’s revenue through costs, expenses and net income.
The key insight: $699 million of additional revenue generated only $262 million of additional gross profit. Operating expenses increased by $449 million, more than absorbing that gain. Margin pressure therefore began before sales, research and administrative spending entered the picture.
Operating income declined 32.7% to $385 million, with operating margin falling from 16.8% to 9.4%. Research and development spending rose 27.5% to $956 million, while sales and marketing increased 20.4% to $1.27 billion.
Several expenses help explain the difference between reported and adjusted earnings:
Excluding those specified items, ServiceNow reported non-GAAP operating income of $1.34 billion, up 17.4%. However, adjusted operating margin still declined from approximately 33.5% to 32.6%. The pressure was not confined to the expenses excluded from management’s adjusted measure.
The acquisition context matters. ServiceNow’s announcement completing its Armis acquisition followed its Veza acquisition. Armis adds cyber-asset visibility, while Veza adds identity-access governance—capabilities intended to connect security intelligence with automated responses.
Debt’s carrying value reached $7.52 billion, compared with $1.49 billion at year-end 2025. Quarterly interest expense consequently increased from $6 million to $81 million.
With interest income also falling, the company moved from $109 million of net interest income to $12 million of net interest expense. That $121 million swing compounded the operating-profit decline. Diluted earnings per share fell from $0.48 to $0.27.
The takeaway: ServiceNow continues to expand revenue, but profitability is not keeping pace. As its platform reaches further into AI, customer workflows and cybersecurity, the central financial test is converting that broader offering into stronger margins while absorbing acquisition costs and a materially larger financing burden.
Last updated: October 29, 2026