Loading blog posts...
April 28, 2026 • 3 min read
For those of us tracking the pulse of the global travel and hospitality sector, earnings reports from industry giants are always a treasure trove. Today, our goal is to dig into the operational updates and income statement from Hilton Worldwide Holdings Inc. (HLT) to see how things are going and what we can learn from their latest 10-Q filing.
For readers who might be less familiar, Hilton is a dominant force in the global hospitality market, operating primarily under an "asset-light" model. Rather than owning the real estate outright, they predominantly franchise and manage hotel properties globally across well-known brands like Waldorf Astoria, Curio Collection, and DoubleTree. They compete head-to-head with heavyweights like Marriott, Hyatt, and IHG.
Let's take a look at the financial flow of Hilton's first quarter of 2026.
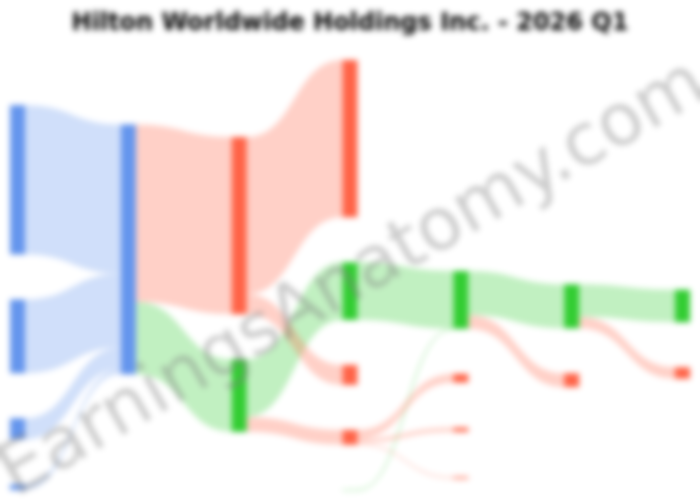
The following chart breaks down Hilton's revenue and expenses for the first three months of 2026, showing how the company arrived at its net income.
A key takeaway from the chart is the significance of the "Cost reimbursement" revenues and expenses. These are essentially pass-through funds where Hilton acts as an intermediary for services at managed hotels, so focusing on the core business lines gives a clearer picture.
Hilton’s total revenues climbed to $2.94 billion for the quarter, up from $2.70 billion in the same period last year. The real story is where that growth came from. The high-margin Franchise and licensing fees jumped 11.4% to $696 million. According to the filing, this boost was driven by both new hotel additions and a $32 million increase in termination fees. This highlights the strength and profitability of Hilton's core asset-light strategy.
This revenue growth translated impressively to the bottom line. Operating income surged over 26% to $678 million, and net income attributable to Hilton stockholders grew 28% to $385 million.
Beyond the income statement, Hilton's operational metrics show a healthy, growing business. A critical industry metric, Revenue per Available Room (RevPAR), grew 3.6% system-wide. This was a result of both higher occupancy (up 1.4 percentage points to 67.4%) and a higher average daily rate (ADR), which rose 1.5% to $157.14.
Performance varied by region:
Hilton also continued its aggressive expansion. The company added a net 10,900 rooms to its system in the quarter, representing 6.3% year-over-year unit growth. Even more telling is its development pipeline, which now stands at a massive 527,000 rooms, signaling a clear path for future growth.
Hilton's management showed confidence by returning significant capital to shareholders, repurchasing over 2.7 million shares for approximately $821 million during the quarter.
In summary, Hilton's first-quarter results paint a picture of a company firing on all cylinders. The asset-light business model is effectively converting steady travel demand into strong, high-margin fee growth. While the occupancy dip in the MEA region is worth monitoring, the robust development pipeline and strong performance elsewhere suggest Hilton is well-positioned for continued success.
Last updated: April 28, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.
Hilton Q3 2026 Earnings: Asset-Light Model Drives 27% Net Income Surge
Oct 28, 2026
Read
Hilton Q2 2026: Fee Growth Shines as Reimbursements Mask Margins
Jul 30, 2026
Read
Hilton's 2025 10-K: Analyzing the Asset-Light Growth Engine
Feb 12, 2026
Read
Hilton Q3 2025 Earnings: Revenue and Profit Surge
Oct 23, 2025
Read