Loading blog posts...
October 30, 2026 • 3 min read
Ford’s third-quarter income statement shows why headline earnings alone can be misleading. A closer look at its Q3 2026 Form 10-Q helps separate operating performance from taxes and restructuring—and reveals how financing profits and smaller electric-vehicle losses offset pressure on its core vehicle businesses.
Revenue fell 2% to $49.5 billion, while net income attributable to Ford dropped 16% to $2.05 billion, or $0.50 per diluted share. Yet adjusted earnings improved modestly.
Ford reported $1.45 billion in operating income, down 7%, leaving an operating margin of 2.9%, versus 3.1% a year earlier. Cost of sales declined by $1.26 billion, more than the revenue decline, but selling, administrative, and other expenses rose 12% to $3.08 billion, eroding that benefit.
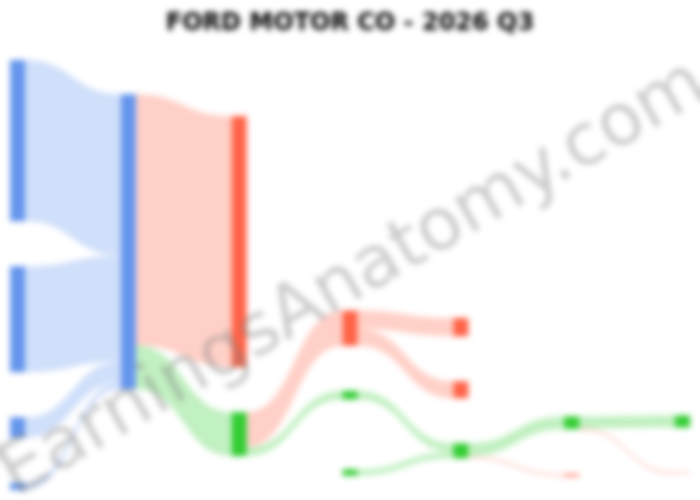
The quarterly revenue-to-profit breakdown is shown below.
Below operating income, other income and affiliate earnings contributed a combined $1.08 billion, before $385 million of automotive interest expense. That contribution included a $320 million pension remeasurement gain—an accounting adjustment to retirement obligations, not vehicle-selling profit.
Despite weaker operating income, pretax income rose 18% to $2.15 billion. Net income nevertheless declined because the prior-year quarter benefited from a $630 million tax benefit, compared with a $97 million tax expense this quarter.
Ford’s adjusted EBIT, a non-GAAP measure excluding specified special items and automotive interest and taxes, increased 3% to $2.66 billion. Adjusted diluted earnings rose from $0.45 to $0.49. These measures complement, rather than replace, the reported results.
The segments explain the modest adjusted improvement:
These segment figures are EBIT—or EBT for Ford Credit—not consolidated operating income. The key takeaway: smaller EV losses and stronger financing earnings more than offset declining profits at Blue and Pro. Model e’s improvement was not a sales-growth recovery.
For the first nine months, operating income increased from $2.39 billion to $4.42 billion on nearly flat revenue. But results also absorbed $3.63 billion in special charges tied to the BOSK joint-venture disposition.
BOSK is BlueOval SK, Ford’s battery partnership with South Korea’s SK On. Coverage of the breakup provides context for this substantial reshaping of Ford’s battery investments.
Nine-month consolidated operating cash flow fell 36% to $11.1 billion, while capital spending rose 17% to $7.04 billion. Adjusted free cash flow declined to $4.9 billion.
Ford guides to $10.5–$11.0 billion in full-year adjusted EBIT, while flagging commodity headwinds approaching $2.5 billion. Against rivals such as GM and Tesla, the central challenge remains improving vehicle profitability while funding an EV transition whose losses are shrinking—but remain substantial.
Last updated: October 30, 2026
Explore prior quarterly filings, historical revenue breakdowns, and earnings trends.